wellnessfitpro
Gloomy picture for retailers in Christmas quarter, economists warn
Economists are warning there could be more gloom ahead for retailers as they enter into the crucial final quarter of the year – which includes Christmas.
Paul Dales, chief UK economist at Capital Economics, said:
October’s sharp fall in consumer confidence and the dip in retail sales volumes in September show that times are getting tougher for households just as the all-important festive period for retailers is just around the corner.
In itself, the 0.4% m/m fall in retail sales volumes in September (consensus -0.1%, CE 0.0%) isn’t bad as it followed a 0.7% m/m rise in August, which was revised up from the first estimate of 0.5% m/m. Admittedly, some of it was due to a 2.2% m/m rise in fuel sales as households topped up their tanks before fuel prices rose even further. They are unlikely to do the same in October. But equally, part of the 0.9% m/m fall in sales at clothing stores was due to the unusually mild weather limiting sales of the new autumn/winter ranges. Soft clothing sales also contributed to the 0.4% m/m drop in sales at supermarkets. Both may perform better in October. Either way, total sales rose by a decent 0.7% q/q in Q3 as a whole.
That all said, the plunge in the GfK measure of consumer confidence, from -13 in September to a six-month low of -24 in October, shows that rising fuel and utility prices, higher borrowing costs and the fear of tax rises in the budget are taking a bigger toll on households. On the face of it, that’s consistent with the annual growth rate of retail sales volumes slowing from 0.8% in September to well below 0%.
This supports our view that both real consumer spending and real GDP will grind to a halt in Q4 and Q1. And this fall in consumer confidence is also the kind of thing that makes the prime minister less likely to call an early election soon.
Jacqueline Windsor, head of retail at PwC UK, noted that fashion retailers had fared the worst in September, despite the warm weather.
Although all other retail categories saw sales rise year-on-year, rising petrol prices meant that consumers had to divert more of their spending on filling up their cars – over 30% more than last September – meaning less to spend on other things.
So, while retail prices, and grocery prices in particular, have remained subdued thanks to industry competition and the delayed pass-through of cost increases due to the conflict in the Middle East, the higher-than-expected inflation reported earlier this week will inevitably translate into less in shoppers’ pockets in the critical run-up to Christmas.
With most retailers’ sales coming in the last three months of the year, the upcoming peak season remains on a knife edge. This time last year, uncertainty surrounding the late budget at the end of November held back spending in the preceding two months. While that makes this year’s comparisons easier, retailers will be hoping that anything announced by the Chancellor this year does not add further to their cost of doing business nor dent consumers’ sentiment, which already seems to have fallen from the highs at the end of summer.”
Introduction: Global stocks wobble as AI fears grow
Good morning, and welcome to our rolling coverage of business, the financial markets, and the world economy.
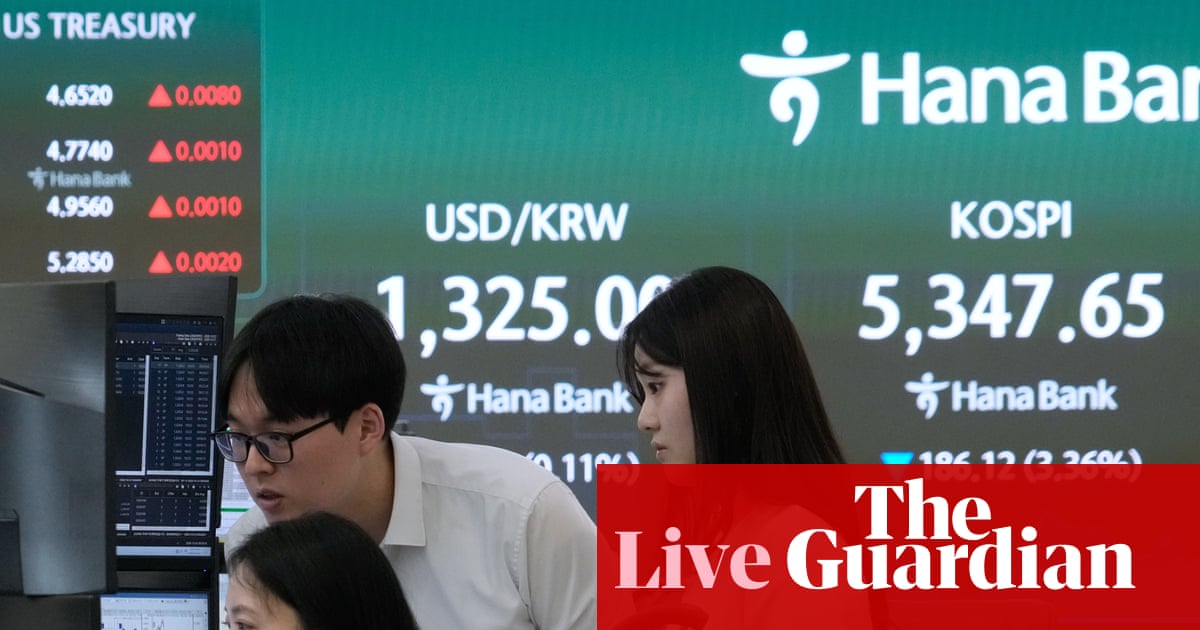
A fresh wave of selling hit AI stocks around the world overnight, as investor grow increasingly anxious around the sustainability of AI-fuelled returns.
The Japanese and South Korean stock markets, which have been buoyed up by their exposure to the AI investment boom, fell before recovering some ground to trade broadly flat on the day.
And over in the US, the blue chip S&P 500 fell by 1.2%, its worst performance since July, and the tech heavy Nasdaq dropped by 2.6%, its biggest drop since June. The Philadelphia semiconductor index fell by a painful 6.7%, also its worst day since June.
Jim Reid, of Deutsche Bank, says our gloomy weather is reflected in the stock market:
As storm Austen hits these shores this morning, clouds kept darkening for markets yesterday, as the wobbles of recent weeks all collided at once. First, there was mounting stress around France, with the Franco-German 10yr spread (+14.8bps) seeing its biggest daily widening since the initial pandemic turmoil in March 2020.
Second, AI fears continued to gather pace, with the Philly semiconductor index (-6.72%) falling to its lowest level since July, which dragged down equities more broadly. And third, the latest geopolitical fears meant oil prices kept rising as well, with Brent crude (+4.00%) hitting a 5-month high of $113.17/bbl.
So collectively, those concerns drove a huge risk-off move, with the 10yr Treasury yield (-16.6bps to 4.95%) seeing its biggest daily decline since August 2024.
And in a further sign that investors are taking a decidedly more conservative approach – there has been a strong move towards US Treasuries, widely considered the best quality government debt in the market and a safe haven asset. Reid says:
…In the midst of all these market pressures, an interesting theme was the flight to US Treasuries, which returned to its traditional risk-off role in periods of turmoil. In fact, the 10yr yield fell -16.6bps to 4.95%.
Moreover, that came despite some strong US data, demonstrating how the financial stress was weighing on sentiment rather than the fundamentals. For instance, the weekly initial jobless claims fell to a 3-month low of 194k in the week ending October 17 (vs. 200k expected). And in turn, that pushed the smoother 4-week moving average to its lowest since September 2022, back when the unemployment rate was just 3.5%.
Ipek Ozkardeskaya, an analyst at Swissquote, says that the falling value of some of the biggest tech and AI stocks in the world suggests that the bubble in the sector is bursting.
Given the more than 50% retreat in memory chipmakers’ share prices from their peaks, we could now argue that their exponential rise was a bubble, and that the bubble has burst.
These memory chip companies continue to benefit from strong AI-related demand, and they’re trading at very low forward earnings multiples: Samsung and SK Hynix at around 3–4× — yes, 3–4 times! Alas, buyers are nowhere to be found.
Investors will be watching closely next week as Microsoft, Google, Amazon and Sandisk are all due to report their latest results.
Elsewhere this morning, British retail sales fell by 0.4% in September, compared with expectations of a drop of 0.1%.
An unseasonably warm start to the autumn weighed on online clothing vendors and supermarkets also saw a drop in volumes, official figures showed on Friday.
Thomas Pugh, chief economist at RSM UK, said:
The drop in retail sales in September and sharp fall in consumer confidence in October raises the risk that the economy’s recent run of resilience might be coming to an end.
At least part of the drop in retail sales in September can be attributed to warm weather dampening demand for winter clothing, which might reverse in October.
But retailers also reported lower footfall and customers cutting back, suggesting cost of living pressures might be starting to bite. Indeed, the slump in consumer confidence in October suggests that higher inflation and borrowing costs are now having a bigger impact on confidence and spending. Nervousness ahead of what seems likely to be another tax raising budget, may also be playing a role.
The agenda
-
7am BST: British retail sales
-
9am BST: Flash PMI for Eurozone
-
9.30am BST: Flash PMI for UK, construction statistics for Great Britain 2025
-
11.30am BST: Russia’s interest rate decision
-
3pm BST: Flash PMI for US, University of Michigan’s US consumer confidence index
#Global #stocks #wobble #fears #grow #retail #sales #Great #Britain #fall #September #shoppers #cut #business #live #Business