wellnessfitpro
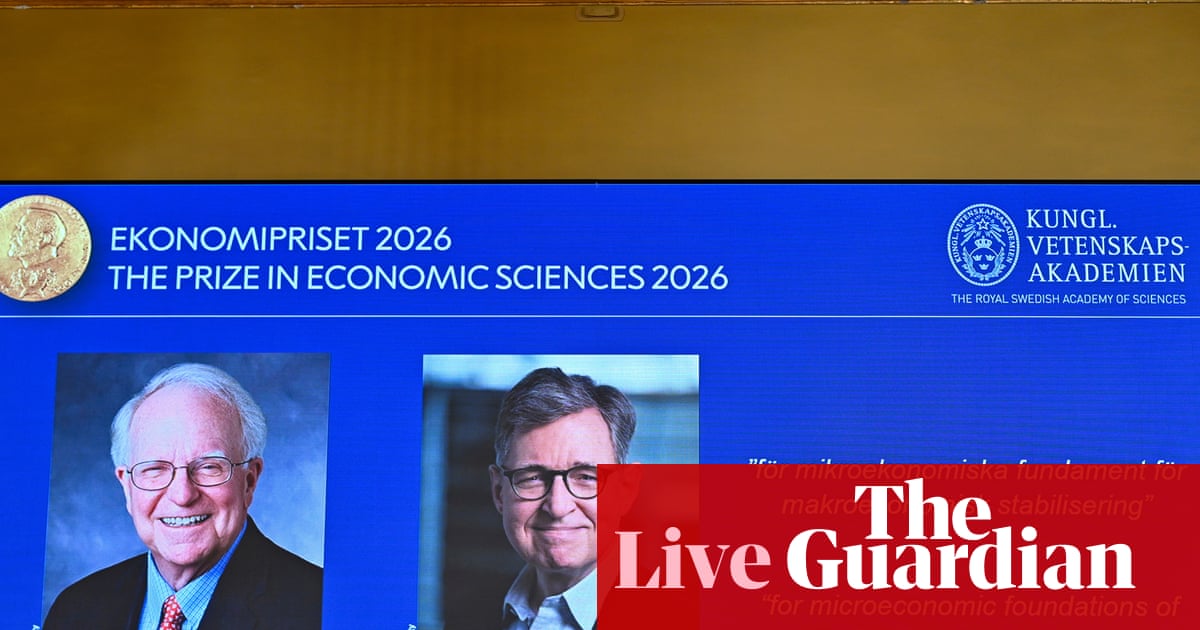
Twenty-five years ago Tyler told me he thought Robert Hall should win the Nobel. He has been a contender for so long today’s award was a surprise! Hall has an unusual number of unexpectedly creative papers. His best known is on consumption.
Start with the Keynesian model, or at least the textbook version: Y = C + I + G + NX. Consumption is the biggest piece of Y and it depends on Y, so C and Y have to be solved together. The consumption function was the engine of the Keynesian multiplier. The simplest version was C = a + bYd, where Yd is disposable income. Economists estimated b, forecast Y and used the forecast to predict C. Get b wrong and you get fiscal policy wrong; so a lot of work went into estimating the consumption function.
Hall began instead with Milton Friedman’s permanent income hypothesis. Consumption today should depend not just on today’s income but on a consumer’s expected lifetime or permanent income. Hall added rational expectations, so people estimate their permanent income using everything they know. Many economists already accepted both ideas. Hall showed that together they imply something surprising. Consumption should follow a random walk!
Suppose you learn today that you will get a large, permanent raise starting next January. If you can save and borrow, you should start spending more today. When January’s bigger paycheck arrives, it isn’t news. You already knew it was coming.
So information that predicts your income should not predict changes in your consumption. Expected changes in income are already built into your spending plans, and only surprises cause revisions. In the simplest case (quadratic utility, free borrowing and saving, and an interest rate that just offsets impatience) the theory gives
Et(Ct+1 − Ct) = 0
Given what you know today, your best guess for the change in consumption is zero. Consumption moves only on news. Past income shouldn’t help predict tomorrow’s consumption once you know today’s consumption.
Hall’s test needed no model of how people forecast income. The old consumption functions used things like a distributed lag on past income as a stand-in for expected future income. Hall asked a different question: does anything known today predict the change in consumption tomorrow? He found that the theory was surprisingly correct! Consumption look like a random walk. Changes in consumption are unpredictable. Since then there are lots of bits nibbling on the edges but overall the theory looks good.
The methodological change was enormous. Instead of merely estimating a relationship between income and spending, economists could test restrictions implied by forward-looking choice. John Cochrane’s account of learning macroeconomics at Chicago describes how deeply Hall’s approach entered the profession’s way of thinking.
This is Hall’s most famous paper but he wrote many others….coming soon.
Hall was part of the New Monetary Economics–Tyler wrote the book on this (alas hard to get) and see also our podcast. Hall’s contribution was a proposal for a commodity standard but not a gold or silver standard. Under a gold standard the price level moves with the relative price of gold, which swings around a lot. Hall’s alternative was to define the dollar as a fixed bundle of ammonium nitrate, copper, aluminum and plywood which he called the ANCAP standard. He chose those four because a price index of the bundle had tracked the CPI closely since the war, so pegging the dollar to the bundle would have come close to stabilizing the cost of living. He didn’t want the government stockpiling fertilizer and plywood. Private arbitrage would keep paper dollars tied to the basket. Hall offered it more as an exploration of what a commodity standard could do than as a policy he was campaigning for. Tyler has said nice things about it. And yes, ANCAP also abbreviates anarcho-capitalism. I assume that’s a coincidence.
Hall’s most famous policy idea is the flat tax, written with Alvin Rabushka at Hoover. It began as a Wall Street Journal op-ed in 1981 and became the book The Flat Tax in 1985. The design is clever. Workers pay a single rate on wages above a generous family allowance. Businesses pay the same rate on revenue minus wages, minus purchases from other firms, minus investment, which is expensed immediately. Interest, dividends and capital gains go untaxed at the household level because the business has already paid. Add it up and you have a consumption tax, a VAT that lets workers deduct an allowance so the system keeps some progressivity. Most households could file on a postcard.
Flat tax bills appeared in Congress through the 1980s and 1990s and Steve Forbes ran on it in 1996 and 2000 but we never passed a fla tax. The idea did shape the Tax Reform Act of 1986, which cut rates and broadened the base, but the mortgage interest deduction, the charitable deduction and every other carve-out had a constituency, and the constituencies won. Public choice explains this one pretty well.
Abroad, however, the flat tax took off. Estonia went first in 1994. Russia adopted a 13 percent flat tax in 2001, and its revenues held up well enough to set off a second wave. Slovakia, Georgia, Romania, Bulgaria and a long list of others followed. Post-communist countries were building tax systems from scratch, without decades of entrenched deductions, and with lots of evasion that a simple low rate could reduce. Rabushka keeps the flags of about thirty countries in his Hoover office. A few later backed away, Slovakia among them.
Most of the foreign versions were flat-rate income taxes. The Hall-Rabushka plan exempted saving and investment, which makes it a consumption tax, and few countries adopted that part. Estonia came closest. It eventually stopped taxing corporate profits until they were paid out as dividends, which is the Hall-Rabushka logic applied to the business side.
The post The Nobel Prize Goes to Robert Hall and Michael Woodford appeared first on Marginal REVOLUTION.
#Nobel #Prize #Robert #Hall #Michael #Woodford